Simeon F. answered 09/03/26
Masters in Finance and Research Associate at $80bn+ Asset Manager
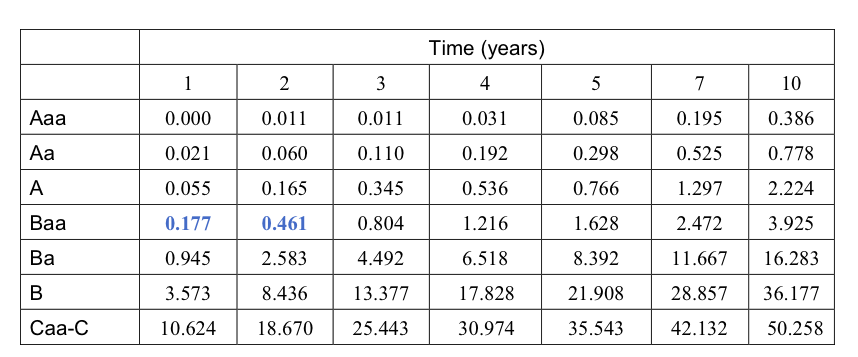
I believe you find the bond rated A and the time period 2 and 3 and take the probabilities .345 and .165 and subtract them to find your answer.
Romina R.
asked 02/13/23Use the following cumulative average default rates % (1970-2016, Moody’s) for bonds that started with a certain credit rating (Table 19.1 in the textbook) to answer the questions.
What is the probability of default between 2 and 3 years from now for a bond initially rated A?
Simeon F. answered 09/03/26
Masters in Finance and Research Associate at $80bn+ Asset Manager
I believe you find the bond rated A and the time period 2 and 3 and take the probabilities .345 and .165 and subtract them to find your answer.
Get a free answer to a quick problem.
Most questions answered within 4 hours.
Choose an expert and meet online. No packages or subscriptions, pay only for the time you need.